 The Ledford Group
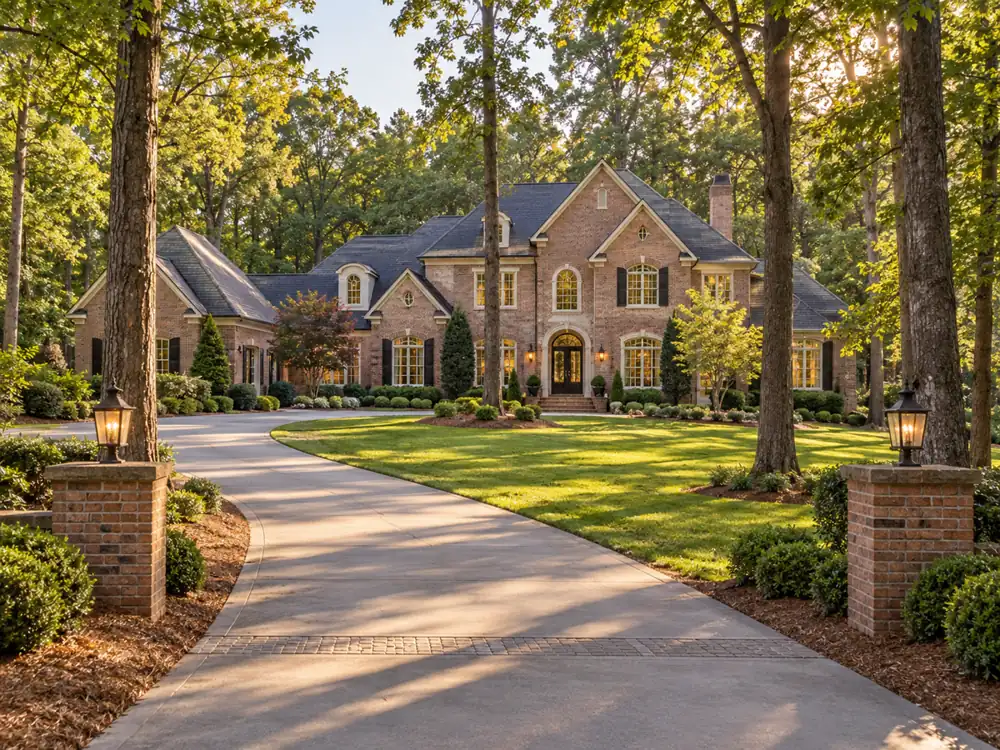
If your Marvin home works for you and your mortgage is at 3%, you don't have to move. If the house has become too much to manage, the 3% matters less than most people think, because a downsizing sale usually leaves you with far less to borrow.
Quick Answer: Freddie Mac's average 30-year mortgage rate was 7.03% on September 24, 2026, so a new loan costs far more per dollar than a 3% loan. But a downsizer who sells a larger Marvin home often buys the next one with mostly their own equity, which shrinks the new loan. Jennifer Ledford of The Ledford Group at eXp Realty recommends running both numbers, keeping and moving, before you decide.
I'm Jennifer Ledford with The Ledford Group at eXp Realty. A line I hear from downsizers is, "I have too much home." Another is, "I don't want this to drag on for months." Neither means you have to rush. See the real numbers first.
What is the 3% mortgage worth?
Here's an example. These numbers are made up to show the math, so use your own.
Say you owe $300,000 and have about 22 years left at 3%. Your principal and interest payment is about $1,554 a month.
Now say you borrowed that same $300,000 today at 7.03% for 30 years. Your payment would be about $2,002 a month. That's about $448 more, or about $5,376 a year.
So the low rate is worth real money. If you stay, you keep it. I'm not going to tell you it doesn't matter.
But does it follow you into the next home?
No, and that's the part many people miss. A conventional loan doesn't follow you to the next house. What matters is how much you'd need to borrow for the next one.
Say your Marvin home sells for $1,000,000. You pay off the $300,000 loan and assume selling costs of about 6%, or $60,000. That leaves about $640,000. Your costs may differ.
If you buy a $700,000 home, you'd borrow about $60,000. At 7.03% over 30 years, that's about $400 a month in principal and interest.
If you buy a $900,000 home, you'd borrow about $260,000, and the payment would be about $1,735.
Compare that with $1,554 a month on your current loan. In the first case, the payment drops by about $1,150. In the second, it goes up by about $181. Those numbers don't include property tax, insurance, or utilities.
What does your current home cost to keep?
That's the other side of the math. Add up property tax, insurance, utilities, lawn care, repairs, and any HOA dues for the home you're in now. Then price those same things for the home you'd buy.
Most people never add these up, because the bills arrive one at a time. Put them in one column. Equity is the other piece, and many downsizers have more of it than they think. A real net estimate takes a few minutes: https://the-ledford-group.com/home-value?utm_source=blog&utm_medium=blog&utm_campaign=2026-10-01-marvin-blog
When does staying make sense?
I'd lean toward staying if you love the home, your payment and upkeep are comfortable, and you don't have a reason to move in the next few years. A 3% loan is an asset, and there's no deadline.
I'd lean toward moving if the stairs, the yard, or the upkeep cost you more than money. If you'd buy mostly with cash from the sale, the old rate wouldn't follow you anyway. And waiting for a lower rate is a bet. The Federal Reserve raised its target rate on September 16, according to CBS News, and nobody knows where rates go next.
What does a Marvin downsize look like day to day?
Marvin doesn't have a downtown, and that's by design. Marvin Efird Park has walking trails and open green space, Stonecrest Shopping Center has a Whole Foods about 5 to 10 minutes away, and Life Time Ballantyne has a pool, spa, and classes. Owners in established neighborhoods like Marvin Creek and Providence Downs South often want to stay near those things, so smaller homes nearby are a fair place to start.
If you're curious what your home would sell for, start with the home value tool: https://the-ledford-group.com/home-value?utm_source=blog&utm_medium=blog&utm_campaign=2026-10-01-marvin-blog
I'll show you the data and what your net might look like. If the numbers say stay, I'll tell you that too. You can also call me at 704-607-6996.
This is general information and not financial advice. Talk to your lender and tax adviser before you decide.
Frequently asked questions
Does my 3% mortgage transfer to a new home? No. A conventional mortgage is paid off when you sell. Your next home would need a new loan at current rates, or you could buy with the cash from your sale.
How do I figure out what I'd net from selling my Marvin home? Start with the likely sale price, subtract your loan payoff and estimated selling costs, and what's left is your approximate net. A real estimate from your agent is better than a guess.
Should I wait for rates to drop before I downsize? It depends on how much you'd borrow. If you'd buy mostly with equity, the rate matters less. If you'd borrow a lot, run the payment at today's rate and at a lower one before you decide.
Is it okay to stay in my home? Yes. If the home works, the payment is comfortable, and you have no reason to move, staying is a sound choice. A real estimate of your net is still worth having so you know your options.
About Jennifer Ledford: Jennifer Ledford is a licensed real estate agent with The Ledford Group at eXp Realty LLC, serving buyers and sellers across Mecklenburg, Union, Stanly, and York Counties since 2016. She is among the top 3% of 18,000+ agents in the Charlotte Metro, an eXp ICON, and has guided 250+ clients through some of the most significant transactions of their lives. Reach her at 704-607-6996 or https://the-ledford-group.com.
Jennifer Ledford | 📞 704-607-6996 | 🌐 https://the-ledford-group.com
About the author
Jennifer Ledford, REALTOR, has helped Charlotte-area buyers and sellers full time since 2016, with 250+ homes sold. She is a Certified Negotiation Expert with The Ledford Group at eXp Realty LLC.
Book a Call with JenniferKeep reading
Marvin Ridge High School: Programs and What Buyers Should Know
October 30, 2026
Moving My Parents In: What Should a Multi-Generational Home Have, and What Do Marvin Homes Offer?
October 28, 2026
Fall Checklist for a Big-Lot Marvin Home: Gutters, Heating, Irrigation, and Septic Before Winter
October 26, 2026