 The Ledford Group
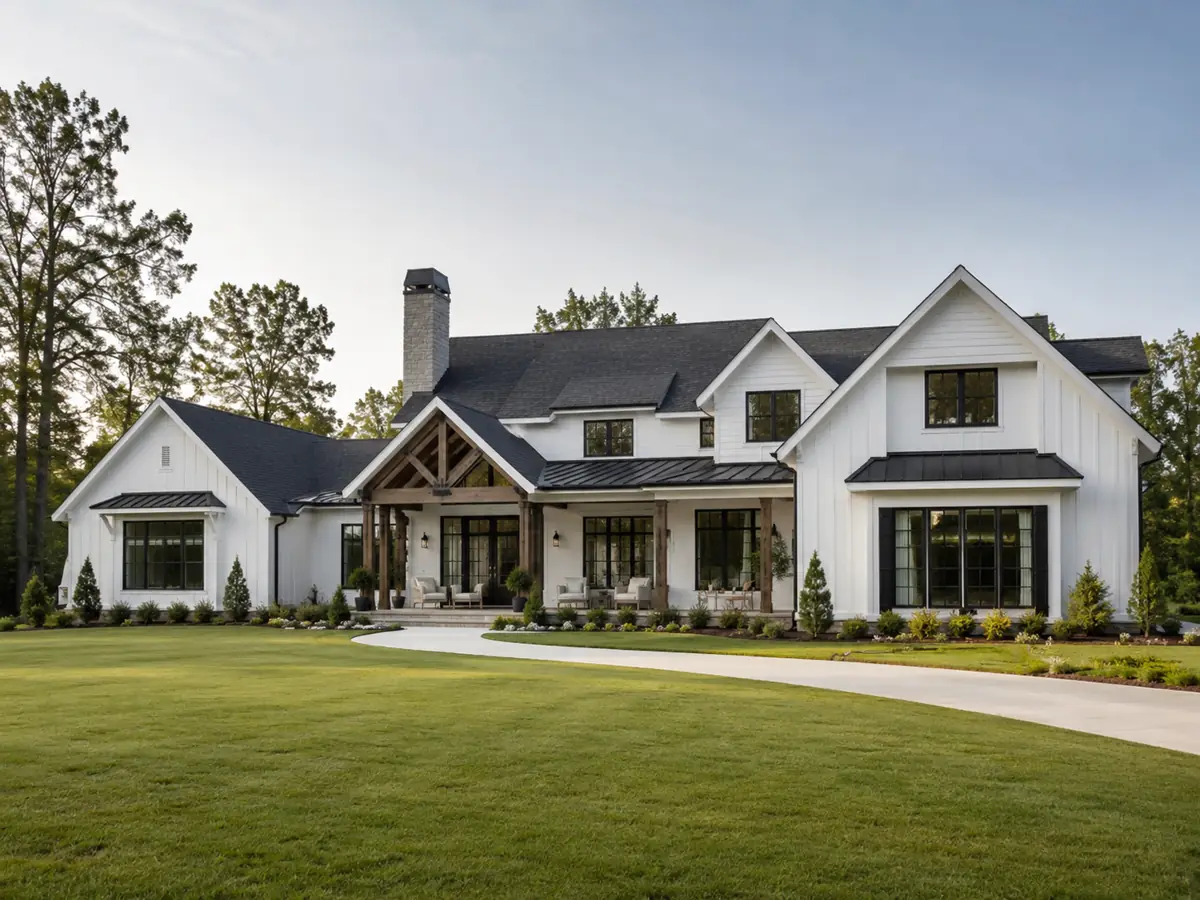
Mortgage rates just touched their highest point in over a year, and if you're shopping for a home in Marvin right now, you probably felt that news land in your stomach a little. Here's the short version: it changes your monthly payment, but it doesn't change whether Marvin is still worth buying into. Let me walk you through what's actually happening and what I'd tell you if we were sitting across from each other right now.
Quick Answer: Mortgage rates climbed to 6.71% as of September 3, 2026 according to Freddie Mac, the highest level in more than a year. For Marvin buyers, that means a higher monthly payment on the same loan amount, but it doesn't erase the value of buying in a market like Marvin where inventory is still tight and demand hasn't slowed. I'm Jennifer Ledford, and after 10+ years working the Marvin market, I can tell you this rate move is real, but it's not a reason to sit on the sidelines if you're ready.
Why did rates jump so fast?
The 30-year fixed rate averaged 6.71% as of September 3, 2026, according to Freddie Mac's weekly survey. Yahoo Finance had it at 6.67% just two days later on September 5. Either way you slice it, this is the highest rates have run in over a year, and most of the move traces back to oil prices and geopolitical tension overseas rattling the bond market. Rates follow the 10-year Treasury, and the 10-year has been jumpy for weeks.
I've helped 250+ buyers and sellers in the Charlotte Metro navigate rate swings like this one, and here's what I've learned: rates move in cycles, and trying to perfectly time the bottom almost always costs people more than it saves them. The Mortgage Bankers Association expects rates to hold between 6.6% and 6.7% through the rest of 2026. Fannie Mae's range is a touch higher, 6.7% to 6.8%. Neither one is predicting a big drop before the year ends.
What this actually costs you on a Marvin home
Marvin homes run $600,000 to $2,000,000+, so the rate move hits differently depending on where you're shopping. On a $750,000 loan, the difference between 6.2% (where rates sat back in the spring) and 6.71% today works out to roughly $220 to $240 more per month. That's real money. It's also not the kind of number that should decide whether you buy a house you actually want to live in for the next ten years.
Where buyers are actually looking in Marvin right now
If you're shopping Marvin at this price point, you've got real variety depending on what you want. The Preserve at Marvin is pulling buyers who want established trees and a settled feel over brand-new construction, it's one of the neighborhoods I point clients to when they tell me they don't want a house that still smells like drywall. Marvin Commons and Providence Downs South both give you newer construction with more consistent floor plans, which tends to appeal to relocating families who want to move in and be done.
As a listing specialist in Marvin, I've seen firsthand that buyers who widen their neighborhood search instead of fixating on one street end up closing faster and with less stress. If your heart is set on one subdivision, that's fine, but know you might be trading speed for specificity.
Rate buydowns and other ways to soften the hit
A higher rate doesn't mean you're stuck accepting it at face value. Two tools I walk almost every Marvin buyer through right now: a seller-paid rate buydown, where the seller credits money at closing to lower your rate for the first year or two, and a permanent buydown, where you pay points upfront to lock a lower rate for the life of the loan. In a market like Marvin where sellers still have leverage because inventory is tight, buydowns aren't guaranteed, but they're a real conversation to have on any offer, especially on a home that's sat on the market a little longer than average.
The other piece worth understanding is an adjustable-rate mortgage with a longer fixed period, five, seven, or ten years. If you know you'll likely refinance or move within that window anyway, an ARM can shave real money off your rate compared to a 30-year fixed. It's not right for everyone, but I'd rather you hear about the option from me than find out later you paid more than you needed to.
Who's actually buying in Marvin right now
Marvin draws two kinds of buyers almost every time. The first is the executive relocating for a role with a company headquartered near uptown Charlotte or out toward the Ballantyne Corporate Park, someone who wants the commute manageable but the house private and spacious. The second is the move-up family already living in South Charlotte or Waxhaw who's outgrown their current home and wants more land without leaving the school district orbit they've come to rely on.
Both buyer types tend to care less about shaving a quarter point off their rate and more about getting the right house before someone else does. That's not me pushing urgency for the sake of it, it's what I've watched happen over and over in this specific market. Marvin's limited land means the right house at the right price doesn't sit long, rate environment or not.
Should you wait for rates to drop?
Here's my honest answer: probably not, and here's the math behind it. If rates ease down to 6.4% or 6.3% sometime next year, that's a meaningful payment savings. But home prices in Marvin haven't been dropping while rates sit high, they've mostly held steady because so few sellers are listing. If you wait a year and rates drop half a point but the home you wanted sold to someone else or the price crept up another 3%, you haven't actually won anything.
The buyers I'm working with right now who are moving forward anyway are doing two things: locking a rate they can live with today, and planning to refinance if rates drop later. A mortgage rate is not a life sentence. A house you love that fits your family is worth more than a perfect rate you might get by waiting for something that isn't guaranteed to happen.
If you're weighing whether now is the right time to sell your current home before buying in Marvin, I wrote a full breakdown on Weddington Preserve that covers how a similar decision plays out for a comparable luxury buyer. And if a rate move like this has you rethinking your own home's value, find out what your home is worth and we can talk through your specific numbers.
What I'd tell a client sitting across from me today
Jennifer Ledford, top 3% agent among 18,000+ in the Charlotte area, explains it like this to every client who walks in nervous about rate headlines: the rate is one piece of the math. It's not the whole picture. What matters more is whether you can comfortably afford the payment at today's rate, whether the home actually fits your life, and whether you're buying in a market that holds its value. Marvin checks the third box about as well as any market in the Charlotte Metro. Large lots, well-known school zones, and a limited supply of new land keep this market resilient even when rates climb.
If a rate quote has you second-guessing your timeline, let's run your actual numbers together instead of guessing from a headline. That's a five-minute conversation, not a big commitment.
Marvin doesn't have its own downtown, and that's by design. Buyers here trade a walkable Main Street for privacy, space, and quiet. When my clients want dinner out, they head ten to fifteen minutes to Postino Ballantyne for wine and small plates, or 131 MAIN Restaurant for something more special-occasion. For groceries and quick errands, Stonecrest Shopping Center, anchored by Whole Foods, covers most of what a Marvin family needs without a long drive. On weekends, families walk or bike the trails at Marvin Efird Park, and if you want a bigger outdoor day, Cane Creek Park is twenty minutes away with fishing, hiking, and camping.
Families choosing Marvin are almost always doing it for the schools. Marvin Ridge High and Marvin Ridge Middle consistently rank among the top-performing schools in the Charlotte Metro, and that reputation shows up directly in how fast homes move and what they sell for. If you want a deeper look at how down payment options are opening up for buyers at a different price point, I broke down what's changing for first-time buyers in Indian Trail this week too.
Frequently asked questions
Will mortgage rates go back down before the end of 2026? Most forecasts don't show a big drop coming. The Mortgage Bankers Association expects rates between 6.6% and 6.7% through the rest of the year, and Fannie Mae's forecast runs slightly higher at 6.7% to 6.8%. Small moves are possible, but nothing suggests rates falling back to 5% territory anytime soon.
Is it a bad time to buy in Marvin because rates are high? Not necessarily. Rates are one part of your total cost, but Marvin's limited inventory has kept prices stable, which matters just as much as the rate itself. Buying a home you can afford today and refinancing later if rates drop is often smarter than waiting indefinitely for a perfect number.
How much does a rate increase actually change my monthly payment? On a $750,000 loan, moving from around 6.2% to 6.71% adds roughly $220 to $240 to your monthly payment. It's worth running your exact numbers since loan amount, credit score, and down payment all affect the math differently.
What neighborhoods in Marvin have the most inventory right now? The Preserve at Marvin tends to offer more established, resale inventory, while Marvin Commons and Providence Downs South lean newer construction. The current active listing count by neighborhood is something I can pull for you directly from MLS.
About Jennifer Ledford: Jennifer Ledford is a licensed REALTOR with The Ledford Group at eXp Realty LLC, serving buyers and sellers across Mecklenburg, Union, Stanly, and York Counties since 2016. She is among the top 3% of 18,000+ agents in the Charlotte Metro, an eXp ICON, and has guided 250+ clients through some of the most significant transactions of their lives. Reach her at 704-607-6996 or https://the-ledford-group.com.
Jennifer Ledford | 704-607-6996 | https://the-ledford-group.com
About the author
Jennifer Ledford, REALTOR, has helped Charlotte-area buyers and sellers full time since 2016, with 250+ homes sold. She is a Certified Negotiation Expert with The Ledford Group at eXp Realty LLC.
Book a Call with JenniferKeep reading
Marvin Ridge High School: Programs and What Buyers Should Know
October 30, 2026
Moving My Parents In: What Should a Multi-Generational Home Have, and What Do Marvin Homes Offer?
October 28, 2026
Fall Checklist for a Big-Lot Marvin Home: Gutters, Heating, Irrigation, and Septic Before Winter
October 26, 2026